Market Structure
Funding payments are not a deposit yield
Funding receipts depend on a derivative position, its notional and its price risk. They are one component of the return.
A periodic funding receipt can look like interest on a balance. Its economic denominator is different: the payment is attached to a derivatives position.
Coinbase’s perpetual-style futures overview describes funding transfers between position holders and a calculation based on funding rate, position quantity, contract multiplier and mark price. Contract mechanics must be checked for the specific product; a displayed rate alone does not describe its cash flows.
Start with position notional
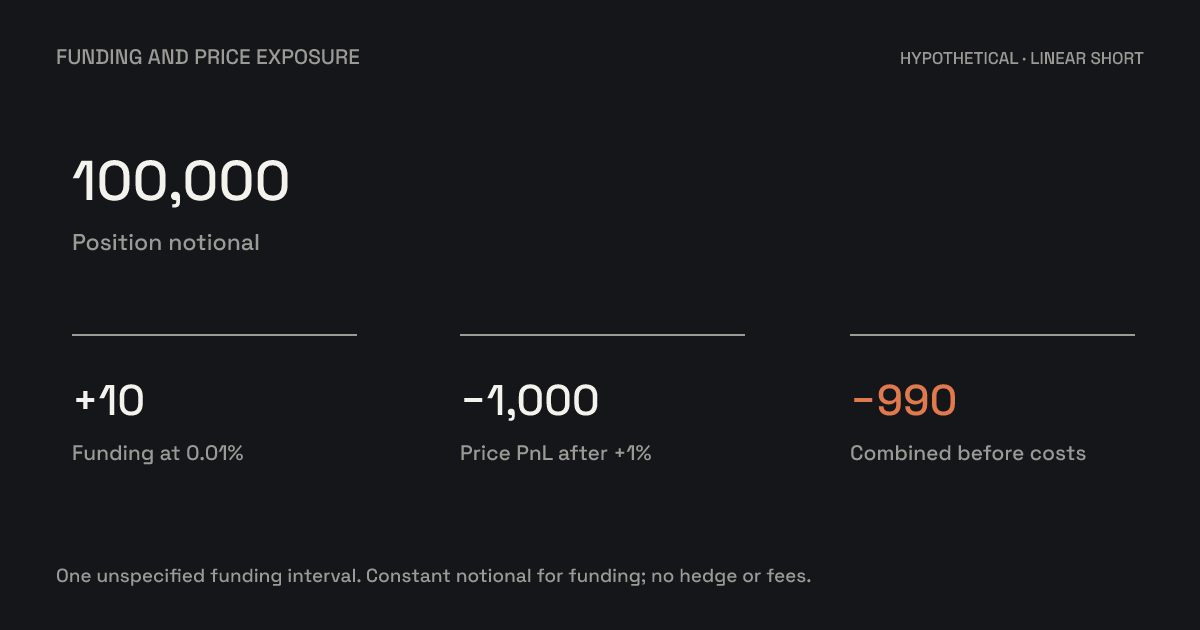
Assume a hypothetical linear contract has a position notional of 100,000 units and pays the short holder 0.01% for one funding interval. Hold that notional constant for the calculation.
Funding received = 100,000 × 0.01% = 10 units.
If 10,000 units of collateral support the position, the payment equals 0.10% of posted collateral for that interval. It remains 0.01% of position notional. Neither number, by itself, is the strategy’s return.
These inputs are hypothetical. The interval is deliberately unspecified; do not interpret this as an hourly quote or an annual yield.
Include the price exposure
Under the same simplified linear model, a 1% rise in the underlying price creates a 1,000-unit loss on the short. A 10-unit funding receipt leaves a 990-unit loss before other costs.
A spot position of matching size could offset that price move approximately under an idealised hedge. It also requires capital or borrowing, two execution legs and operational access to both positions. Any mismatch between spot and derivative prices changes the result.
The hedge therefore needs its own accounting. Include spot and derivative price changes, funding actually settled, entry and exit fees, borrowing costs and any residual exposure. Collateral supporting one venue may not be immediately available to cover losses on another.
Test the sign as well as the rate
A strategy expecting to receive funding can face a change in direction. Analyse a scenario in which the position pays instead, and specify how long the strategy can support the resulting cash outflow.
For comparison with a lending product, use total strategy equity as the return denominator and the actual holding period as the time basis. Keep the derivative’s notional visible as a separate exposure measure.
Funding can contribute income. Whether that income compensates for the position’s risks is a question about the whole trade, its capital and its exit.
Mechanics source checked in October 2026. This conceptual archive edition does not assert historical Coinbase contract terms or funding rates for January 2026.