Research
The same BTC exposure, different funding signs
Across 69 aligned settlements, Binance and Bybit BTCUSDT funding had opposite signs 30 times.
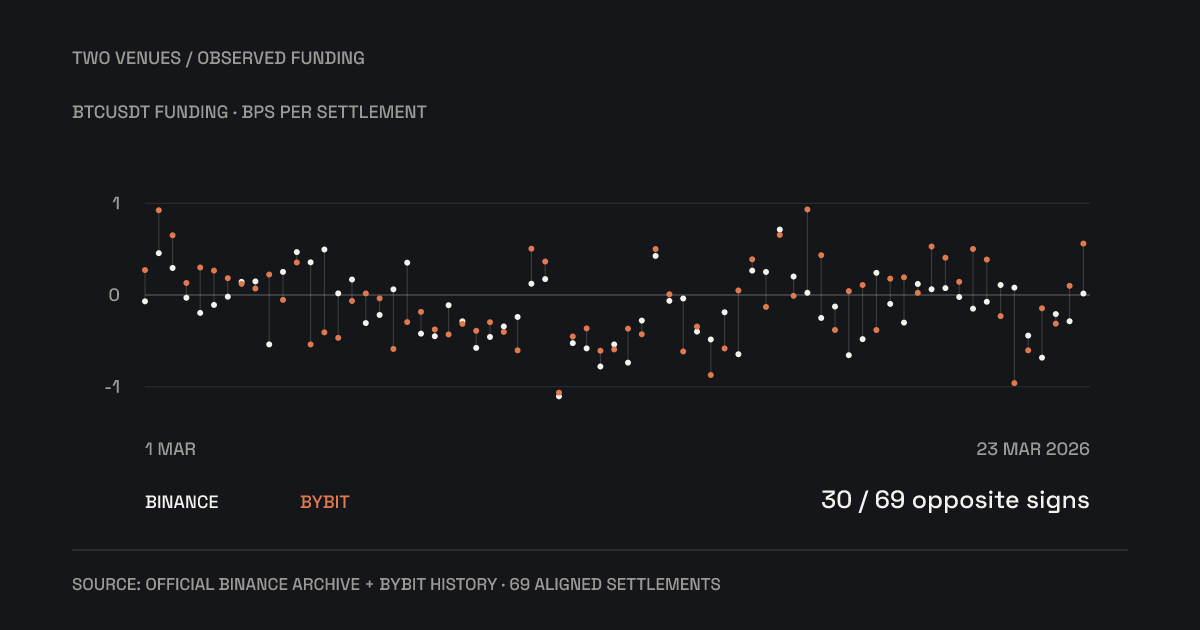
Two BTC perpetual positions can face different funding conditions at the same time. In a bounded comparison of Binance and Bybit BTCUSDT USDT-margined perpetuals, the funding rates had opposite signs at 30 of 69 aligned settlement moments.
That is a finding about realised funding-rate histories. It does not establish a profitable cross-venue trade.
What we compared
We used Binance’s official March 2026 funding archive and Bybit’s historical funding endpoint. The observation window covers settlement timestamps from 1 March 2026 at 00:00 UTC through 23 March at 16:00 UTC. The first timestamp is a settlement boundary, not the start of a newly opened position.
There are three matching observations per day across 23 days, with no missing timestamps in the selected window. Binance’s records specify eight-hour intervals. Bybit’s returned timestamps follow the same eight-hour grid. Binance calculation timestamps sit 0–14 milliseconds after those boundaries; we align them to the nearest boundary and preserve the original offsets internally.
The histories are available through Binance’s public-data service and Bybit’s documented funding-history endpoint. Rates are expressed below in basis points per settlement: one basis point is 0.01%.
The difference changed direction
| Measurement | Observed result |
|---|---|
| Opposite non-zero funding signs | 30 of 69 settlements |
| Bybit rate above Binance rate | 40 settlements |
| Binance rate above Bybit rate | 29 settlements |
| Median absolute rate difference | 0.3231 bps per settlement |
| Sum of Binance rates | −8.4163 bps |
| Sum of Bybit rates | −4.3681 bps |
At 00:00 UTC on 22 March, Binance’s rate was +0.0806 bps while Bybit’s was −0.9613 bps. This was the largest absolute difference in the sample: 1.0419 bps.
Under the documented funding sign convention, positive rates mean longs pay shorts; negative rates reverse that direction. At that observed moment, a long would therefore have faced different payment directions on the two venues.
A rate sum is not a strategy return
Adding rates gives a simple comparison under a constant-notional convention. Bybit minus Binance totals 4.0482 bps across the sample. On a hypothetical constant 100,000 USDT notional per leg, that corresponds to 40.482 USDT of gross funding difference for long Binance and short Bybit.
That illustration requires notional rebalancing; a fixed BTC quantity would have changing notional as prices moved. Neither calculation includes opening and closing costs, basis changes, margin requirements, transfers or liquidation exposure. Historical fees and executable cross-venue quotes were not collected for this study.
The result supports comparing aligned histories rather than a single displayed rate. It does not support annualising the sample into an expected return or choosing a venue without checking the cost and risk of holding the position there.
Archive edition: March 2026. Prepared in October 2026 from the selected historical observations. This two-venue, one-contract sample is descriptive and does not establish persistence outside the window.