Research
Small median execution costs can hide a wider tail
A one-day Bybit BTC/USDT spot study shows how book-only execution estimates change with order size—and why a median is an incomplete summary.
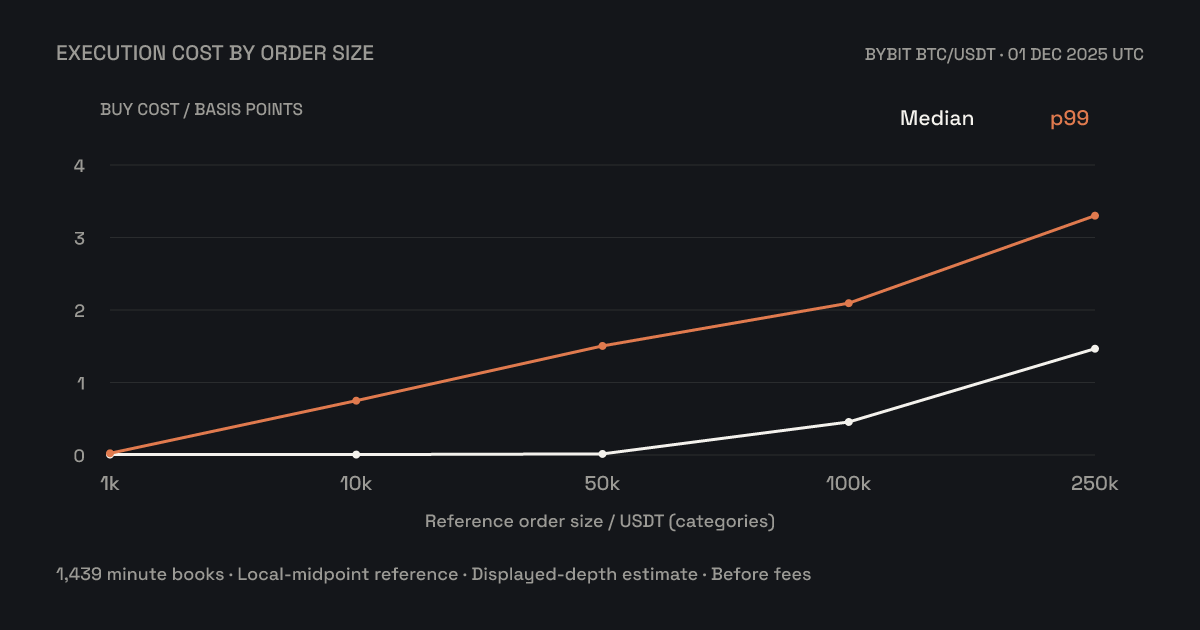
Study scope: Bybit BTC/USDT spot · 1 December 2025 UTC · 1,439 minute-boundary books · Estimated execution before fees and latency.
Buying approximately 250,000 USDT of BTC cost about 37 USDT above midpoint value in the median observation. At the 99th percentile, that estimate was about 83 USDT—more than twice as much.
The order size was the same. The available liquidity changed through the day.
This is why a median execution estimate needs company. It describes the centre of the sample, while the more expensive observations reveal conditions that a typical number can hide.
What changes as the order grows?
For each reconstructed book, we estimated the price of buying five different sizes by consuming the displayed asks from cheapest to most expensive. Each size fixes a BTC quantity using that book’s midpoint; actual spending includes the resulting price concession.
| Reference size, USDT | Median cost, bps | p99 cost, bps | Median excess, USDT | p99 excess, USDT |
|---|---|---|---|---|
| 1,000 | 0.0058 | 0.0233 | 0.00 | 0.00 |
| 10,000 | 0.0058 | 0.7493 | 0.01 | 0.75 |
| 50,000 | 0.0150 | 1.5044 | 0.08 | 7.52 |
| 100,000 | 0.4553 | 2.0942 | 4.55 | 20.94 |
| 250,000 | 1.4661 | 3.3012 | 36.65 | 82.53 |
One basis point is 0.01%. Costs are measured relative to the midpoint between the same book’s best bid and ask. They include the price concession in crossing to the ask and consuming deeper levels, but exclude trading fees.
At 10,000 USDT, the median barely differs from the 1,000 USDT result, while p99 increases substantially. Looking only at the median would obscure that change.
All five sizes could be fully walked within the published 200 ask levels in every usable observation. That is an observed coverage result for this day, rather than a guarantee that an arriving order would receive those fills.
One actual book: 02:39 UTC
At 02:39 UTC on 1 December, the reconstructed midpoint was 86,625.65 USDT per BTC. A 250,000 USDT reference size therefore meant buying approximately 2.88598123 BTC.
The best ask was 86,625.70, but only 0.005773 BTC was available there—about 500 USDT. The intended purchase had to consume deeper levels.
| Ask price, USDT/BTC | BTC consumed | Purchase value, USDT |
|---|---|---|
| 86,625.70 | 0.005773 | 500.09 |
| 86,626.00 | 0.000300 | 25.99 |
| 86,626.60 | 0.024300 | 2,105.03 |
| Remaining 62 price levels, through 86,667.30 | 2.855608 | 247,451.43 |
The complete walk used 65 ask levels, with an average estimated fill of 86,654.25 USDT/BTC. Total expenditure was 250,082.54 USDT: 82.54 USDT, or 3.3015 bps, above the reference value.
This actual observation was selected because its cost is nearest the sample’s interpolated p99. It illustrates an expensive moment, not a typical one. Table figures are rounded.
How to use the finding
An execution estimate is more useful when it specifies the intended size and shows a distribution, rather than a single typical cost. Here, the upper tail changed materially before that change became obvious in the median.
For a larger trade, compare the median with more expensive observations and check how often the available book covers the whole order. Add the applicable fees separately. A deep snapshot still cannot guarantee that liquidity remains available while an order arrives.
These percentiles describe this sample. They do not establish a future 1% probability of paying the reported p99 cost, or show which exchange would be cheaper.
Method and limits
We selected the latest fully applied book at or before each UTC minute boundary, with a maximum event age of one second. Of 1,440 represented boundaries, 1,439 were usable. Midnight preceded the first native snapshot at 00:00:02.583 UTC and was excluded.
For reference size N, BTC quantity is N / midpoint. Buy cost is (VWAP / midpoint − 1) × 10,000; sell cost reverses the price difference. The calculations cover both directions. Percentiles use linear interpolation at (n − 1) × p.
The supplied reconstruction reported no update-ID gaps for this day. Full-archive CRC and hash checks passed; independent Decimal-key replays matched the complete selected arrays at three boundaries. Other dates are outside those checks.
The estimates assume displayed liquidity remains available. They exclude latency, cancellations during execution, hidden orders and market response. Minute sampling can miss brief dislocations. Historical fees with confirmed effective dates remain unavailable; missing fees have not been treated as zero.
There is one venue and one Monday in this sample. It supports a bounded execution case study, not a December-wide average, a venue ranking or a weekend effect. Observations are serially related, so these are descriptive percentiles, not independent statistical trials.
Archive edition: December 2025. Analysis prepared in October 2026 using observations from 1 December 2025. The broader multi-day, two-venue study remains unfinished.