Developments
Bank custody: a permission is one stage
The OCC’s March 2025 letter changed a supervisory process. Service availability still needs separate evidence.
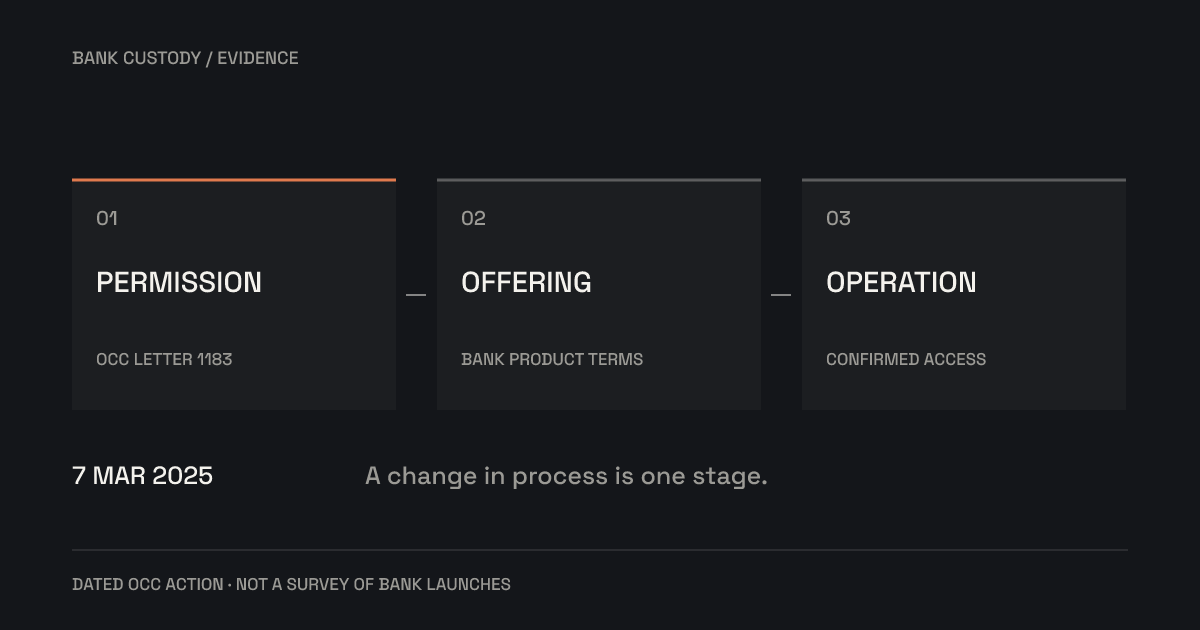
A regulatory announcement can widen a bank’s options without making a service available to its customers that day. The useful question is which barrier changed and which operating steps remain.
The OCC’s 7 March 2025 announcement reaffirmed the permissibility of crypto-asset custody and certain related activities for national banks and federal savings associations. It also removed a prior supervisory non-objection requirement. The announcement is evidence about the supervisory framework for those institutions, rather than a list of customer services that went live.
What the letter changed
Interpretive Letter 1183 rescinded Letter 1179’s process and reaffirmed earlier interpretations. The distinction matters: describing the event as the first time banks could hold crypto would erase the earlier permissions to which the letter itself refers.
The OCC also retained an expectation of strong risk management. Removing a particular prior process does not turn an operational assessment into a formality.
Follow the path to an actual service
For a prospective customer, the next evidence should be a named bank’s product terms. Which assets and networks does it support? Which legal entity contracts with the customer? Who controls signing, and how are instructions authorised?
Then come practical availability and exit. A product announcement should be checked against onboarding eligibility, transfer support and the process for recovering or moving assets. A service open to a defined institutional client group does not establish access for every depositor.
These are due-diligence questions, not findings that any particular bank has failed them. They turn a broad permission headline into a testable description of a service.
Keep the evidence in separate columns
| Stage | Useful evidence | What it does not establish |
|---|---|---|
| Permitted activity | Regulator’s interpretation and institutional scope | A specific bank’s launch |
| Product offered | Bank’s dated terms and eligible-client definition | Completed customer onboarding |
| Service operating | Confirmed access and supported operations | Broad adoption or suitable terms for every client |
The March 2025 event belongs in the first row. Moving to the second or third requires additional evidence from the institution involved.
For market participants, that separation improves comparisons. A permissions change may increase the set of potential providers; competition and usable custody capacity depend on which providers actually build and operate a service.
Archive edition: February 2026. Prepared in October 2026 as an analysis of the dated March 2025 OCC action. This is not a survey of current bank offerings or a statement about every US bank.